
How the GIC calculator Canada works
Enter your deposit, the GIC rate and the term, then choose how interest is paid. If you hold the GIC outside a registered account, add your marginal tax rate to see what you keep after tax. The GIC ladder tab spreads your money over five terms.
The calculator uses annual compounding for multi-year GICs and simple interest for terms paid at maturity, which is how most Canadian banks and credit unions quote them.
GIC interest on $10,000
| GIC rate | 1 year | 3 years | 5 years |
|---|---|---|---|
| 3% | $300 | $927 | $1,593 |
| 4% | $400 | $1,249 | $2,167 |
| 5% | $500 | $1,576 | $2,763 |
Interest earned with annual compounding, before tax.
Rates change often, so check your bank's current rates and type them into the calculator.
GIC interest and tax
Interest is the most heavily taxed type of investment income in Canada. Here is $25,000 earning 3.5% for one year at different marginal tax rates:
| Marginal tax rate | Interest | Tax | You keep |
|---|---|---|---|
| 20.05% | $875 | $175 | $700 |
| 29.65% | $875 | $259 | $616 |
| 43.41% | $875 | $380 | $495 |
| 53.53% | $875 | $468 | $407 |
Example combined federal + provincial rates; yours depend on your income and province.
Holding GICs in a TFSA avoids this tax entirely. In an RRSP, tax is deferred until withdrawal.
Building a GIC ladder
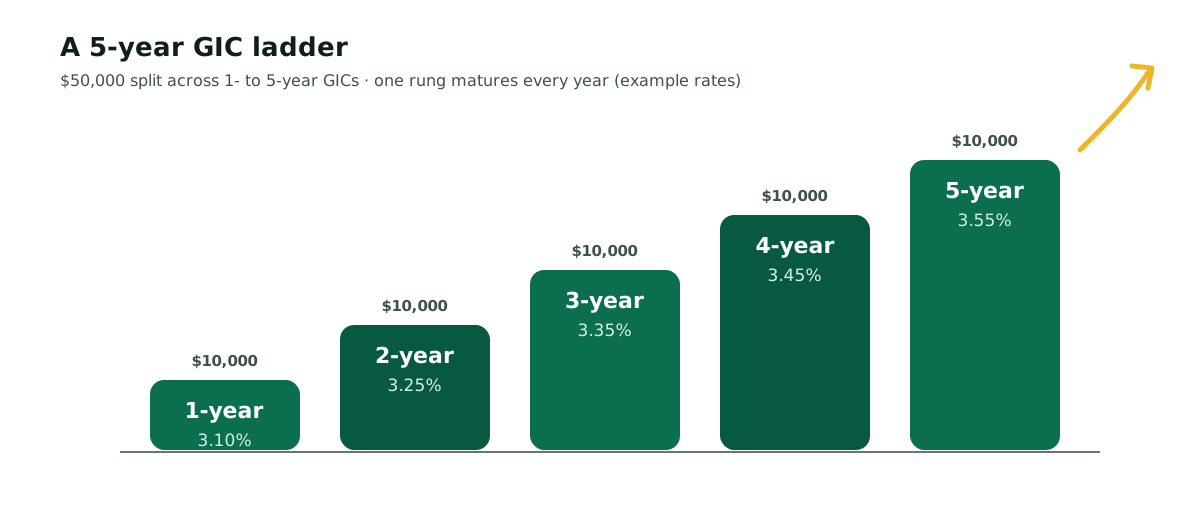
- Split your money into five equal parts.
- Buy 1-, 2-, 3-, 4- and 5-year GICs.
- When the 1-year GIC matures, reinvest it in a new 5-year GIC.
- After four years, every rung earns the 5-year rate and one still matures every year.
Compare the result with a savings account or other investments using the compound interest calculator or the interest calculator Canada.
GIC Calculator Canada – FAQ
How is GIC interest calculated in Canada?
Most GICs longer than a year compound annually: maturity value = deposit × (1 + rate)years. Short-term GICs under a year usually pay simple interest at maturity. Some GICs pay interest monthly or semi-annually instead of compounding.
Is GIC interest taxable?
Yes, outside a registered account. Interest is taxed at your marginal rate. For multi-year compound GICs, you must report the interest that accrues each year, even though you don't receive it until maturity. In a TFSA it's tax-free.
Are GICs safe in Canada?
GICs at CDIC member banks are protected up to $100,000 per insured category (such as TFSA, RRSP, FHSA or non-registered) at each institution. Credit union deposits are protected by provincial insurers.
What is a GIC ladder?
You split your money across GICs of different lengths — say 1 to 5 years. Each year one matures, giving you access to cash and the chance to reinvest at current rates.
Can I cash a GIC early?
Non-redeemable GICs usually can't be cashed before maturity. Cashable or redeemable GICs allow early withdrawal but usually pay lower rates.
Results are estimates for education only. Lenders and financial institutions set your actual rate, payment and terms. See our disclaimer.