
How the compound interest calculator Canada works
Enter what you have today, your expected annual rate, how long you'll save and how much you'll add regularly. The calculator compounds the interest at the frequency you choose and adds your contributions at the end of each period. It then shows:
- your future balance and how much of it is interest,
- the effective annual rate and how long it takes to double,
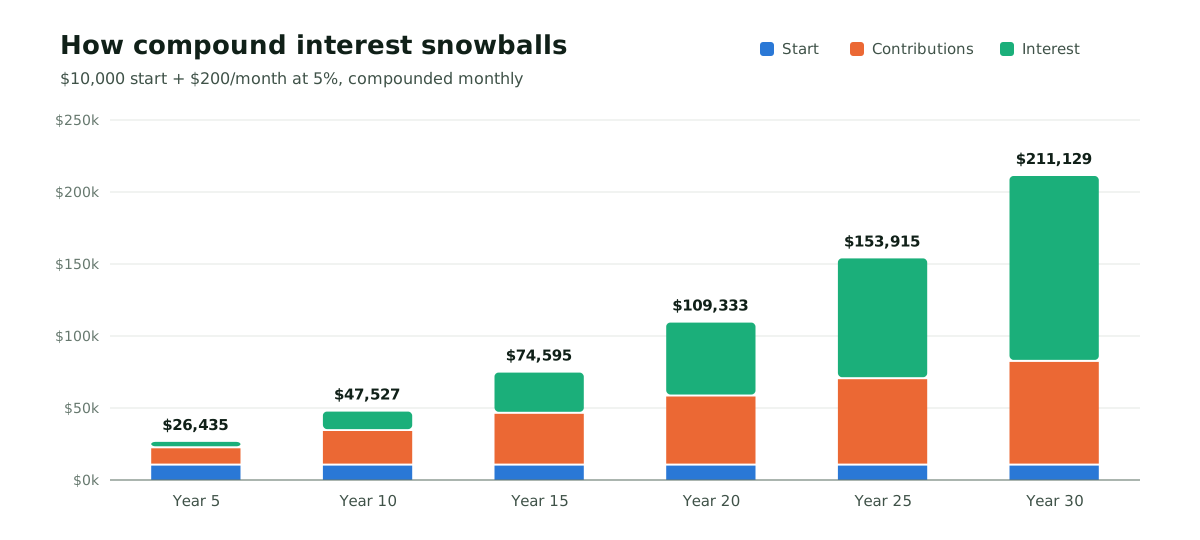
- a bar for every year so you can see the snowball build.
Compound interest in a TFSA
Here's what contributing the full $7,000 a year (about $583 a month) to a TFSA could grow to over 20 years, tax-free:
| Annual return | Total contributed | Balance after 20 years | Tax-free growth |
|---|---|---|---|
| 3% | $140,000 | $191,509 | $51,509 |
| 5% | $140,000 | $239,770 | $99,770 |
| 7% | $140,000 | $303,874 | $163,874 |
Because TFSA growth is never taxed, every dollar of interest is yours to keep.
Why starting early matters
Time is the most powerful input in compound interest. Saving the same $300 a month at 6%:
| Start age | Saving until 65 | Total deposited | Balance at 65 |
|---|---|---|---|
| 25 | 40 years | $144,000 | $597,447 |
| 35 | 30 years | $108,000 | $301,355 |
| 45 | 20 years | $72,000 | $138,612 |
The 25-year-old deposits twice as much as the 45-year-old but ends up with several times more, because the early money compounds for decades.
Ways to make compounding work harder
- Automate contributions on payday so saving happens first.
- Use registered accounts — TFSA, RRSP and FHSA — to keep tax from slowing growth.
- Shop for rates. A 1% higher rate on savings adds up over time; compare with the GIC calculator.
- Pay off high-interest debt first. Clearing a 20% credit card is a guaranteed 20% return.
Want to compare simple interest or plan a target? Use the main interest calculator Canada.
Compound Interest Calculator Canada – FAQ
What is a compound interest calculator?
It shows how a deposit grows when the interest it earns is added back and starts earning interest too. Ours also adds regular contributions and shows the balance year by year.
How often is interest compounded in Canada?
High-interest savings accounts usually calculate daily and pay monthly. GICs usually compound annually. Choose the matching option in the calculator to compare.
Can I use this for my TFSA or RRSP?
Yes. Enter your current balance, expected return and planned contributions. Remember that TFSA growth is tax-free while RRSP growth is taxed when withdrawn.
Should I contribute monthly or yearly?
Monthly contributions start earning sooner, so they usually end up slightly ahead of one yearly lump sum made at year end. Use the contribution frequency buttons to compare.
What return should I assume?
High-interest savings and GICs typically pay a few percent a year. Balanced investment portfolios have historically returned more but with ups and downs. Use a conservative rate for planning.
Results are estimates for education only. Lenders and financial institutions set your actual rate, payment and terms. See our disclaimer.